If you have ever applied for financing in the UAE, you may have noticed that banks ask for a copy of your tenancy contract along with your salary certificate and bank statements. This connection between your rental agreement and your loan file is at the heart of Ejari mortgage approval, and understanding why banks care about this document can help you prepare a stronger application.
This guide explains why Ejari mortgage approval processes rely on tenancy verification, and what it means for your eligibility.
Why Do Banks Verify Tenancy Contracts?
Banks in the UAE are required to follow strict Know Your Customer and anti-fraud procedures before approving any financing. A registered tenancy contract gives them a government-verified record of where you actually live, rather than relying solely on your word. This is a key part of Ejari mortgage approval, since lenders want to confirm your residential stability before committing to a long-term loan.
Verifying your tenancy also helps banks assess your overall financial picture. If your declared income does not reasonably match your rental commitment, it can raise questions during underwriting. This is why tenancy verification often becomes one of the quieter but important checkpoints in the broader Ejari mortgage approval process.
Does Ejari Affect Loan Eligibility?
Yes, in several indirect ways. While Ejari itself is not a credit score or income document, it does contribute to how comfortable a bank feels about your application. A consistent, properly registered tenancy history can support your file, while gaps, unregistered agreements, or frequently changing addresses may prompt additional questions.
Some of the ways Ejari mortgage approval factors into eligibility include:
- Confirming your current residential address matches other submitted documents
- Showing a stable rental history if you have lived in the same property for some time
- Supporting your debt-to-income calculations when your rent is factored into monthly obligations
- Providing a legally recognized document banks can rely on instead of informal proof
Ejari for Bank Loan Applications Beyond Mortgages
It is not only mortgage applicants who encounter this requirement. Ejari for bank loan applications, including personal financing and even some credit card approvals, often ask for a valid tenancy contract as part of standard documentation. Banks use Ejari for bank loan verification because it is a straightforward, government-issued record that is difficult to falsify compared to a simple rental receipt.
If you are applying for financing of any kind, having your Ejari for bank loan documentation ready alongside your Emirates ID, passport, and salary certificate can speed up the review process considerably.
Is Ejari Proof of Residence for Banking?
Yes, Ejari is widely accepted as a valid form of residential verification across UAE financial institutions. Ejari proof of address documentation is commonly listed alongside utility bills and bank statements as an acceptable way to confirm where an applicant currently lives. Since Ejari proof of address comes directly from a government-registered system, many banks consider it more reliable than a simple lease copy that has not been officially recorded.
This is one of the clearest reasons the Ejari mortgage approval process leans so heavily on this document, since it removes ambiguity about an applicant’s actual living situation.
Tenancy Contract Bank Dubai Requirements
When you sit down with a lender in the emirate, a tenancy contract bank Dubai request is almost always part of the checklist. Typical documents banks ask for alongside your tenancy contract bank Dubai submission include:
- Valid passport and UAE visa copy
- Emirates ID, front and back
- Salary certificate addressed to the specific bank
- Last three to six months of bank statements
- Registered Ejari certificate showing your current address
- Trade license, if you are self-employed
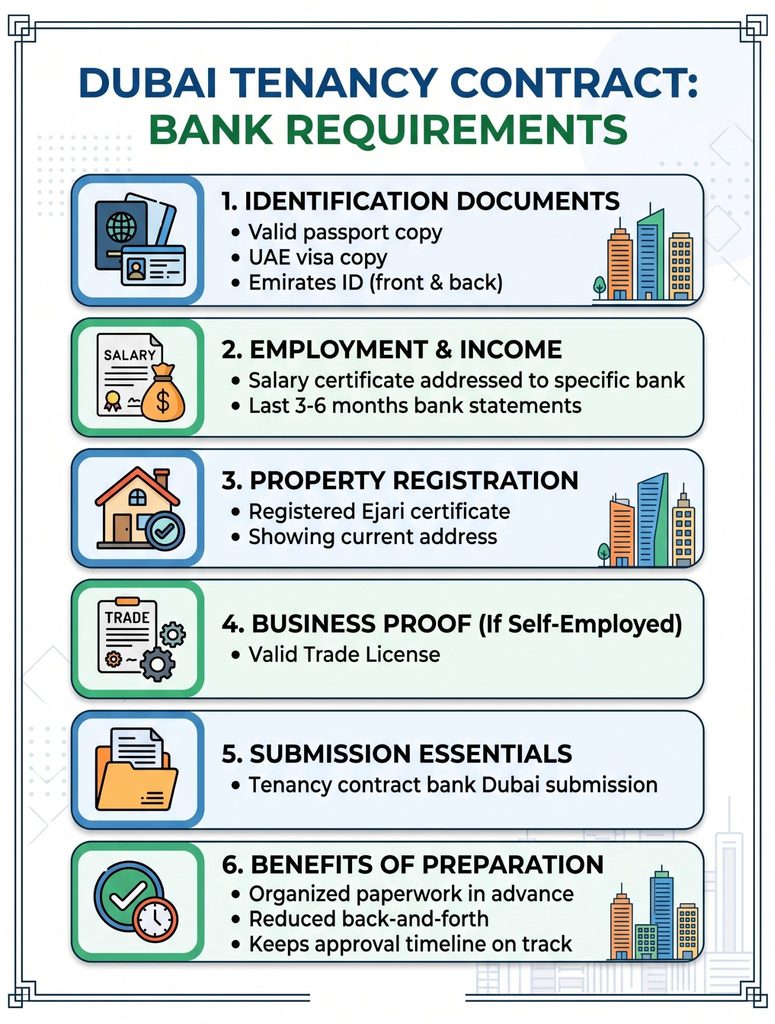
Having your tenancy contract and bank Dubai paperwork organized in advance reduces back-and-forth with your loan officer and keeps the approval timeline on track.
Can I Get a Personal Loan Without Ejari?
In some cases, yes, particularly if you already bank with the institution and have an established relationship, salary transfer, or other strong supporting documents. However, Ejari personal loan UAE requests are still common, especially for applicants who are newer to a bank or whose income documentation needs additional support.
If your file lacks an Ejari personal loan UAE certificate, some banks may accept alternative proof such as a recent utility bill or bank statement showing your address, though this varies by institution and loan type. It is always best to ask your bank directly which documents they will accept if you do not yet have a registered tenancy.
Preparing Your File for Smoother Approval
Since so much of Ejari mortgage approval comes down to having consistent, verifiable paperwork, it helps to get your Ejari certificate sorted early rather than scrambling once you have already started your loan application. A few practical steps include:
- Registering your Ejari as soon as your tenancy contract is signed
- Keeping a digital copy of your certificate ready to upload during applications
- Renewing your Ejari on time so it does not expire mid-application
- Making sure your name and address details exactly match across your Emirates ID, visa, and tenancy documents
Conclusion
Banks in the UAE lean on Ejari because it offers a clear, government-verified way to confirm your address and rental history, which supports both mortgage and personal loan decisions. Understanding how Ejari mortgage approval works helps you prepare a stronger file and avoid unnecessary delays when you are ready to apply for financing.
If you need help registering or renewing your tenancy contract before your next loan application, reach out to the team at Ejari Meydan for guidance on getting your documents in order quickly and correctly.
Frequently Asked Questions
Why do banks specifically ask for Ejari instead of just a lease copy?
An Ejari certificate is government-registered and verified, which makes it a more reliable proof of address than an informal or unregistered lease agreement.
Can an expired Ejari certificate delay my mortgage approval?
Yes, an expired certificate may prompt the bank to request an updated document before proceeding, so renewing on time helps avoid delays.
Does my rent amount affect my loan eligibility?
It can, since some banks factor your rental obligation into your overall debt-to-income assessment when reviewing your application.
Is Ejari required for every type of bank loan?
Not always, but it is commonly requested for mortgages, personal loans, and sometimes credit card applications as part of standard verification.
What should I do if I do not have an Ejari certificate yet when applying for a loan?
Speak with your bank about acceptable alternatives, such as a recent utility bill or bank statement, while you complete your Ejari registration.